Voluntary Benefits

Published by Leah Mellay on October 26th, 2026
I believe everyone should have accident insurance. Not just people with active kids, not just the people with physical jobs or a long list of hobbies. Everyone.
That may seem like an obvious take from someone who sells these benefits for a living. Let me tell you why you can trust it.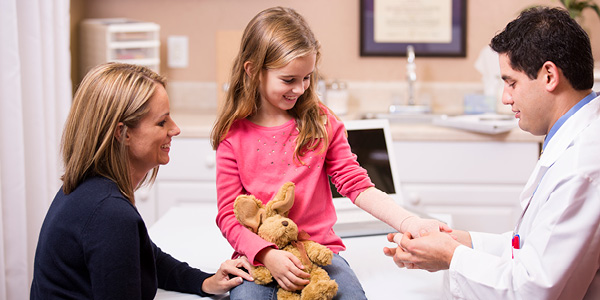
When my daughter Sloane was four years old, she broke her arm — that was claim number one. Every parent knows that moment: the rush to the doctor, the waiting, the hoping it isn’t as bad as it looks. Then the doctor put the X-ray on the screen and started talking through her recovery, and it was enough to knock me off my feet. Literally. I fainted, and that turned into its own accident claim.
That was claim number two. Claim number three came after Sloan finished healing. On the very day her cast came off, she broke her foot.
Three accidents, three claims, and one family that spent a long stretch of time in and out of doctors’ offices. However, outside of the deductible on our medical plan, we had virtually zero out-of-pocket expenses. Instead of worrying about what all of this was going to cost, we got to focus on Sloan.
What they all have in common though is the financial risk that comes with them. Even people with solid medical coverage can face deductibles, copays, and costs they never planned for. For some families, a serious accident can create financial pressure that takes years to climb out of. Some can even lead to bankruptcy. A policy that pays benefits directly to the policyholder helps take the edge off those unexpected events.
There’s the employer side of this to consider, too. When someone is hurt, or when their child or spouse is hurt, their mind is likely not on their job. They’ll be sitting in a waiting room, opening bills, or lying awake doing math. And quite frankly, you can’t blame them.
You can’t expect an employee to be fully present when they are worried about how to pay for what just happened. But accident coverage gives them one less thing to carry, and that helps the employee and the employer.
You don’t have to take my word for it, but you’re welcome to borrow my story. It’s real, it’s recent enough to still feel fresh, and it shows what these benefits look like in action.
If you have a client who could use a real conversation about accident coverage, I’d love to help you have it. Let’s make sure the people you serve are covered for the moments they never see coming.
That may seem like an obvious take from someone who sells these benefits for a living. Let me tell you why you can trust it.
Three Claims in One Very Long Season of Accidents
When my daughter Sloane was four years old, she broke her arm — that was claim number one. Every parent knows that moment: the rush to the doctor, the waiting, the hoping it isn’t as bad as it looks. Then the doctor put the X-ray on the screen and started talking through her recovery, and it was enough to knock me off my feet. Literally. I fainted, and that turned into its own accident claim.
That was claim number two. Claim number three came after Sloan finished healing. On the very day her cast came off, she broke her foot.
Three accidents, three claims, and one family that spent a long stretch of time in and out of doctors’ offices. However, outside of the deductible on our medical plan, we had virtually zero out-of-pocket expenses. Instead of worrying about what all of this was going to cost, we got to focus on Sloan.
Accidents Don’t Check Your Calendar
Our story involved a playground and a pair of bad breaks, but accidents show up in all kinds of ways. Car accidents. Slips on the ice. A Friday night football game. A weekend project that goes sideways.What they all have in common though is the financial risk that comes with them. Even people with solid medical coverage can face deductibles, copays, and costs they never planned for. For some families, a serious accident can create financial pressure that takes years to climb out of. Some can even lead to bankruptcy. A policy that pays benefits directly to the policyholder helps take the edge off those unexpected events.
There’s the employer side of this to consider, too. When someone is hurt, or when their child or spouse is hurt, their mind is likely not on their job. They’ll be sitting in a waiting room, opening bills, or lying awake doing math. And quite frankly, you can’t blame them.
You can’t expect an employee to be fully present when they are worried about how to pay for what just happened. But accident coverage gives them one less thing to carry, and that helps the employee and the employer.
What This Means for Your Conversations
When you sit down with a client or prospect who isn’t sure if voluntary accident coverage is worth offering, remember that you never know who is across the table. The person who says “we’re a healthy group,” may be one fall, one fender bender, or one football season away from needing it. Those are exactly the people who benefit most from having it in place before they need it.You don’t have to take my word for it, but you’re welcome to borrow my story. It’s real, it’s recent enough to still feel fresh, and it shows what these benefits look like in action.
…
I’ve been in this industry long enough to explain how accident plans work in my sleep. But living it with my own kids changed the way I talk about it. I learned firsthand the feeling of relief when you open the mail and find that the financial side of an injury is already handled. That’s why I’m so passionate about these benefits. I’m not just selling them. I use them — sometimes more frequently than I care to admit!If you have a client who could use a real conversation about accident coverage, I’d love to help you have it. Let’s make sure the people you serve are covered for the moments they never see coming.
Share
Author
Written by Leah Mellay
Regional Sales Director,
Alleghany Mountain (PA, WV, Western NY)
Topics