The Strategic Value of $0 Virtual Care: Better Access, Better Engagement, Better Health

Published by Angela Paret on October 21st, 2026
Reducing the cost barrier to virtual care can help employers improve access, support preventive care and condition management, and deliver benefits employees are more likely to use while creating long-term value for employers.
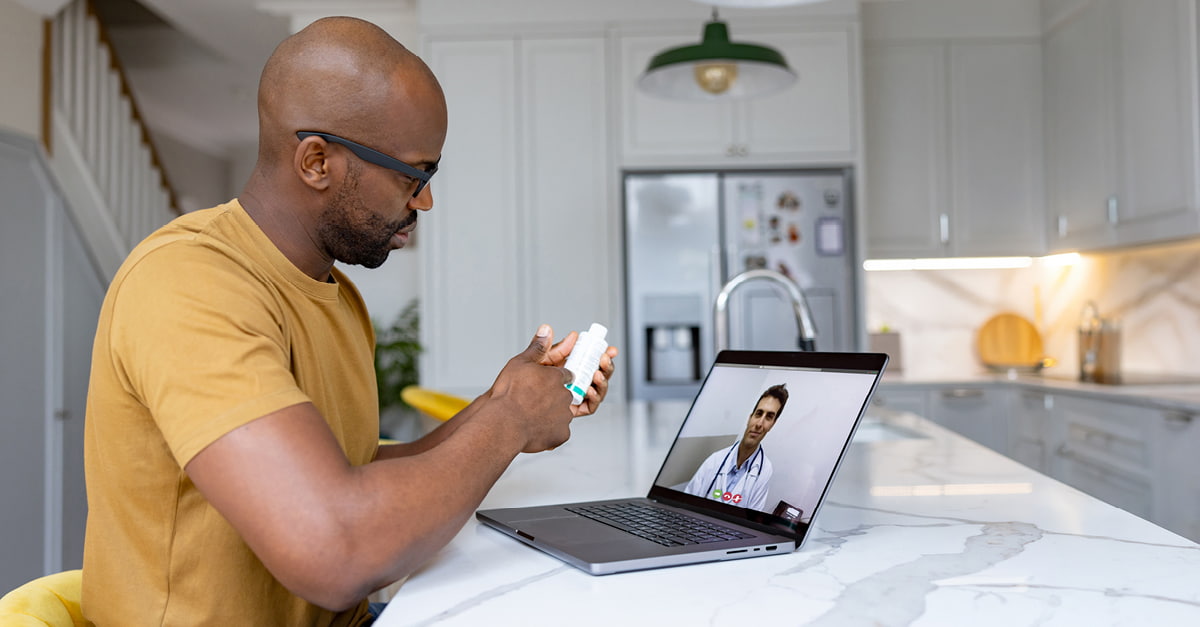 Employers have long faced a frustrating healthcare trade-off. As costs rise, they may feel forced to shift more of the expense to employees or accept that providing more valuable benefits will increase costs.
At the same time, access to care remains a growing challenge. According to data cited by Teladoc® Health, more than 100 million Americans have little or no access to primary care where they live.1 For many employees, the challenge is not simply having health coverage. It's finding available providers, securing timely appointments, understanding costs, and fitting care into busy lives.
Yet a health plan can only deliver value when employees use the care, resources, and support available to them. Higher deductibles, copays, and other forms of cost sharing have become familiar tools for managing healthcare spending, often based on the assumption that controlling costs requires asking employees to take on more responsibility.
Affordability and employee value, however, do not have to be competing priorities. Increasingly, employers, brokers, and health plans are rethinking how healthcare benefits create value, focusing not just on coverage, but on removing barriers to care. One example is $0 virtual care, where Trustmark is leading the move toward benefits that make care easier to afford, access and use. Trustmark's virtual care offering includes services from Teladoc Health Virtual Primary Care2, 24/7 care, mental health services2, and dermatology, and musculoskeletal treatment2 through Vori Health at $0 member cost.
It reflects a simple but important reality: benefits create value only when employees use them. Removing the cost barrier to eligible virtual services can make care easier to access, easier to understand, and easier to use. For employers, that can be an advantage because benefits that employees actually use often create more visible value than benefits that exist primarily on paper.
Healthcare Access Is More Than a Network
Healthcare access is often discussed in terms of provider networks and coverage. Employees experience it differently. For many people, access comes down to practical realities.
- Can they find a provider accepting new patients?
- Can they get an appointment without waiting months?
- Can they fit care into an already busy schedule?
- Do they understand what the visit will cost?
- Do they know where to turn when they need help?
Those questions matter because they influence whether someone seeks care in the first place. That's why healthcare organizations increasingly define access more broadly. Affordability, convenience, appointment availability, transparency, navigation, and support all influence whether members can realistically use a healthcare benefit.
A health plan can offer excellent benefits on paper, but employees may still struggle to take advantage of them if the process feels difficult, expensive, or time-consuming. The challenge is especially visible in primary care, where access often depends on more than having insurance coverage.
For many employees, access is less about whether a provider appears in a directory and more about whether they can realistically get an appointment when they need one. This perspective helps explain why virtual care has become more strategically important. The value isn't simply that an appointment happens virtually. Virtual care can reduce travel time, eliminate waiting rooms, provide more scheduling flexibility, and create another path to care when an office visit is difficult to arrange.
Why Cost Still Gets in the Way of Care
Access is influenced by more than location and scheduling. Cost can also play a meaningful role. Employees make healthcare decisions in the context of competing priorities. A person may decide to wait a few days to see whether symptoms improve. Another may postpone a follow-up appointment because it doesn't feel urgent. Someone else may delay care because they're uncertain about what the visit will cost.
A $0 member cost for eligible virtual services removes some of that uncertainty.
Instead of evaluating whether an appointment is worth the potential expense, employees can focus on whether speaking with a provider would help them address a concern, answer a question, or determine their next steps. The benefit also becomes easier for employers and brokers to communicate because the member cost is straightforward and easy to understand.
That simplicity should not be confused with unlimited free healthcare. Laboratory work, imaging, prescriptions, specialist visits, and other downstream services remain subject to the applicable health plan benefits. Still, removing the member cost for eligible virtual visits creates a clearer starting point. Employees know they can connect with a provider without first calculating the cost of the virtual appointment itself. That easier access may also encourage members to seek guidance earlier, before a health concern becomes more difficult or costly to address.
Virtual Care Is Doing More Than Ever Before
Many people still associate virtual care with treating a minor illness or obtaining quick guidance for an immediate concern. Those services remain important, but virtual care has evolved well beyond its original role.
Today's virtual care offerings may include:
- Primary care
- Urgent care
- Mental health services
- Musculoskeletal (MSK) treatment
- Dermatology
Together, these services can support a wide range of healthcare needs, from everyday illnesses and skin conditions to anxiety, depression, chronic pain, and ongoing health management. For example, members with a major medical Trustmark plan can access MSK support through Vori Health, which focuses on back, neck and joint pain through a virtual care model designed to connect members with the appropriate clinical support for their needs.
This matters because employees do not experience healthcare through product categories. One person may need help managing stress. Another may be dealing with chronic back pain. Someone else may live in a rural area with limited access to a primary care provider or convenient access to preventive care.
A broader virtual care offering recognizes that people need different types of support at different times. It allows virtual care to become more than an occasional convenience. It becomes another way to connect members with appropriate care.
How Virtual Primary Care Differs from Traditional Telehealth
Perhaps the most significant development in virtual care is the growth of virtual primary care. Traditional telehealth often follows a familiar pattern: one issue, one visit, and one resolution. Virtual primary care is designed differently. Members can establish an ongoing relationship with a provider and care team that supports:
- Preventive care
- Wellness needs
- Chronic condition management
- Medication review
- Care planning
- Referrals
- Coordination
- Follow-up care over time
Rather than functioning as a series of disconnected interactions, virtual primary care is designed to create continuity. That continuity can be valuable because many healthcare outcomes are shaped by what happens between appointments, not only during them. A provider who understands a member's health history can help identify gaps in care, recommend screenings and immunizations, monitor chronic conditions, and guide members toward appropriate next steps when additional care is needed.
Virtual primary care is not intended to replace every in-person healthcare interaction. Physical examinations, laboratory services, imaging, and specialty care still play important roles. The goal is to provide members with a consistent healthcare relationship and help them navigate an increasingly complex healthcare system.
For employees who have struggled to establish an ongoing relationship with a primary care provider, that continuity can represent a meaningful improvement in access. In fact, nearly half of Virtual Primary Care participants did not have a primary care provider before enrolling.3 That suggests virtual primary care is often doing more than replacing a traditional office visit. For some members, it is helping create a primary care relationship that did not previously exist.
Why This Matters to Employers
Employers are not simply evaluating benefits. They are evaluating whether those benefits provide meaningful value to employees. A $0 virtual care offering can help address practical challenges employees face every day. Virtual visits can reduce travel time, minimize disruption to work schedules, and provide another option when local provider availability is limited. The clarity of a $0 member cost also makes the benefit easier to understand and communicate.
Virtual primary care adds another layer of value by supporting preventive care, chronic condition management, coordination, and follow-up through an ongoing provider relationship. Instead of helping employees address only immediate concerns, it creates an avenue for more continuous engagement with healthcare.
The broader virtual care offering also allows employers to address several common healthcare needs through connected resources. In addition to primary care, employees may have access to behavioral health support, dermatology services, and musculoskeletal care through Vori Health for back, neck and joint pain. Together, these services can help employees access support earlier and in ways that are often easier to fit into their daily lives.
Ultimately, the value is not simply that another benefit exists. The value is that employees may be more likely to understand it, access it, and use it. Greater engagement with care can help support preventive care, chronic condition management, and healthier outcomes over time.
A Better Conversation for Brokers
For brokers, virtual care has become a more strategic discussion than it was just a few years ago. The key question is no longer whether a health plan includes telehealth. Many plans do. The more valuable question is what employees can actually accomplish through the virtual care offering:
- Does it address multiple healthcare needs?
- Does it go beyond immediate care?
- Can members establish an ongoing primary care relationship?
- Does it support preventive care and chronic condition management?
- Is the member cost simple and easy to understand?
- Can providers help coordinate next steps when additional care is needed?
Those questions reveal far more about the employee experience than a simple checklist of services. They also create a stronger client conversation. Employers increasingly want benefits that are visible, understandable, and easy to use. They want solutions that support employee well-being without introducing more complexity. They want benefits that employees recognize as valuable in their day-to-day lives. A more comprehensive virtual care offering helps brokers connect those priorities to a practical benefit strategy.
Affordability and Member Value Can Work Together
Healthcare costs will continue to challenge employers, and no single solution will solve every issue. But the conversation is evolving. Rather than assuming affordability and employee experience must always compete; many employers are exploring how benefits can create value by removing barriers to care. Virtual care is one example of that shift. When care is easier to access, easier to understand, and easier to fit into everyday life, employees may be more likely to use the resources available to them.
Trustmark's expanded virtual care offering reflects that broader approach. Eligible members now have access to virtual primary care, 24/7 care, mental health services, dermatology, and musculoskeletal treatment at $0 member cost for eligible virtual services. The enhancement is designed to give members more ways to connect with care, including access to an ongoing primary care relationship through virtual primary care. Trustmark does not expect the $0 member cost benefit to increase total plan costs.
For employers, brokers, and employees alike, the larger lesson may be that affordability and member value do not have to be opposing goals. Sometimes the most meaningful improvement is not adding another benefit. It's making existing benefits easier to use. Removing financial and practical barriers can help employees connect with care earlier, navigate the healthcare system more effectively, and get more value from the benefits already available to them.
Trustmark's expanded $0 virtual care offering reflects that philosophy by combining virtual primary care, 24/7 care, mental health services, dermatology, and musculoskeletal treatment into a connected care experience designed to reduce barriers and improve access to care.
Explore the Possibilities
- Explore the virtual care and health support services available to Trustmark members, including primary care, 24/7 care, mental health, dermatology, musculoskeletal care, and other resources.
- See how virtual primary care can support preventive care, chronic care management, and ongoing care coordination.
- Connect with a Trustmark representative to discuss how $0 virtual care can support your (or your client’s) workforce and benefits strategy.
1Health Resources and Services Administration. October 2024. 2Available to covered dependents age 13 and older. 3Teladoc Health BoB VPC Utilization Report: 1/1/24-12/31/24.
About the Author
Angela Paret is Sr. Director, Product Development, Trustmark Small Business Benefits. She develops health benefit solutions that help employers offer meaningful benefits and support employees in accessing care and improving their well-being.
Smarter health plans, backed by experience.
For more than 110 years, Trustmark has been a leader in employee benefits, bringing decades of self-funded expertise to flexible, modern health plans that help employers manage healthcare responsibly.
Trustmark Small Business Benefits® level-funded solutions, which include PPO plans with access to national networks through Aetna® and Cigna® PPO Network, Reference-Based Pricing, and dual-option designs, give employers real transparency, predictable monthly costs, and the potential for surplus refunds. Employees receive benefits they can easily use, and brokers get a partner who has delivered stability and service for decades.
Cigna® is a trademark of Cigna Intellectual Property, Inc. Access provided through the Aetna Signature Administrators solution.
Trustmark® and Trustmark Small Business Benefits® are trademarks of Trustmark Insurance Company. All other trademarks are the property of their respective owners, which are not affiliates of Star Marketing and Administration, Inc., and Trustmark Life Insurance Company.
Plan design availability and/or coverage may vary by state. Self-funded plans are administered by Star Marketing and Administration, Inc., and stop-loss insurance coverage is provided by Trustmark Life Insurance Company.
©2026 Star Marketing and Administration, Inc.
Share
Author
Written by Angela Paret
Angela Paret is Sr. Director, Product Development, Trustmark Small Business Benefits. She develops health benefit solutions that help employers offer meaningful benefits and support employees in accessing care and improving their well-being.
Topics